Closing post
Time to wrap up…
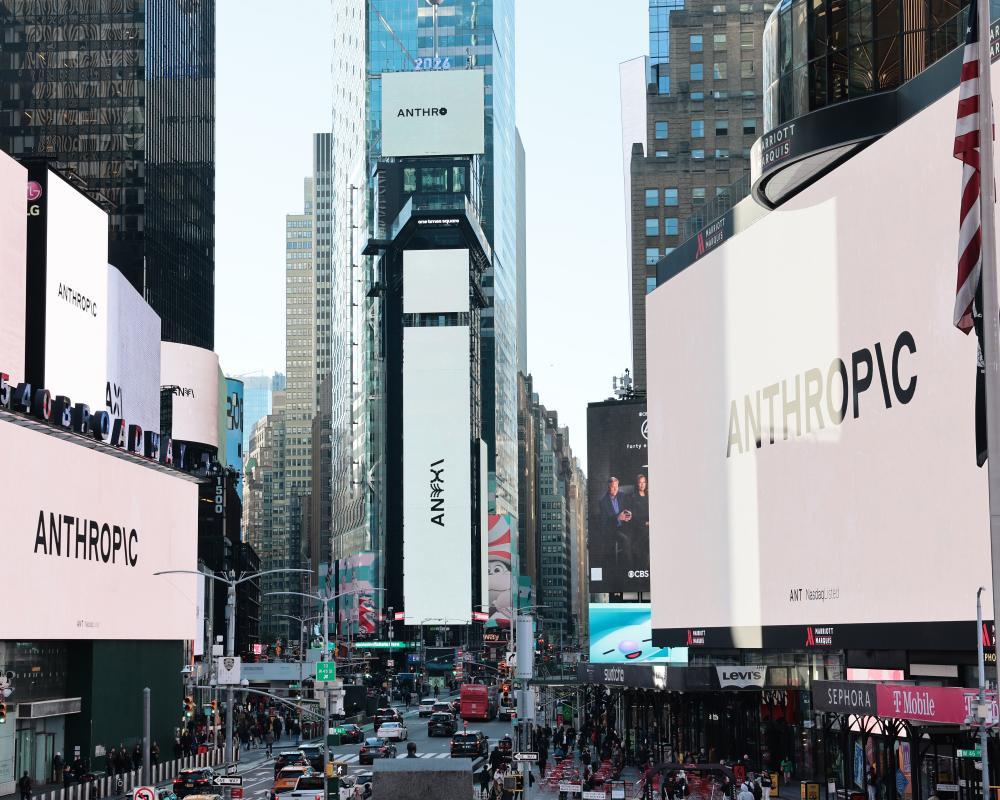
Anthropic’s shares slumped at the start of trading on Friday, as its record-breaking IPO failed to stem a sell-off in AI-linked companies.
Shares in the frontier AI company, which floated on Thursday, fell by over 9% at the start of trading on Friday. They dropped to $88.17, towards the $83 level at which the company sold shares in its IPO this week.
Anthropic’s first two days as a listed company have been volatile. Its shares jumped by 17% on Thursday, after briefly surging by almost 40% when trading in the frontier AI firm began.
Related: Anthropic shares slump on second day of trading as stock markets reel from AI sell-off
The UK and EU have agreed a reset deal, Downing Street has said, although the level of tuition fees EU students will pay to study at UK universities remains unresolved.
“The deal is done – negotiations have concluded,” a No 10 statement said, less than an hour after the prime minister, Andy Burnham, arrived at the summit venue in Brussels, where he was greeted by Ursula von der Leyen, the European Commission president, and António Costa, the European Council president.
The reset means there is agreement on three deals – food and drink, emissions trading, and a youth mobility scheme – but EU sources say these deals will not enter into force unless the UK reaches a settlement with the bloc over tuition fee rates for European students.
The statement came shortly after headlines on Friday suggested that the tuition fee issue could cause other parts of the process to collapse.
However, after the deal was announced, UK officials pushed back strongly against the idea that the three plans could be jeopardised by a failure to agree on tuition fees, saying the issues were completely separate. Earlier, EU officials had indicated that progress on the main deals would be contingent on tuition fees.
Related: Burnham has agreed EU reset deal with tuition fees issue unresolved, says No 10
The UK government borrowed less than expected in October despite a rise in debt interest costs, in a boost for chancellor John Healey amid the pressure on Britain’s economy from the Middle East war.
The Office for National Statistics (ONS) said public sector net borrowing – the difference between government spending and income – was £17bn in October, about £800m higher than the same month a year ago. City economists had forecast borrowing would increase by more, to £18bn.
In the financial year so far, public sector net borrowing was £111.3bn, the ONS said – £7.3bn less than in the same period last year, helped by stronger tax receipts.
Related: UK government borrowing rises less than forecast in surprise boost for chancellor John Healey
Anthropic has recovered some of its earlier losses, and is now down by about 5% on the day. The Nasdaq has also recovered a bit, now down by 0.6%.
More bruising numbers in the US – the Philadelphia semiconductor index, which tracks the country’s biggest chip companies, has just dropped by 4% to hit a two-week low.
The worst performers in the Nasdaq 100 today are SanDisk, Lumentum and Nebius, which are all down between 7-8%. All of them are connected to the AI infrastructure buildout.
CoreWeave is also one of the worst performers, with its shares down 7%.
Updated
Anthropic shares plunge 9% day after historic IPO
Ding ding ding! Anthropic has dropped 9% at the opening bell, in what is only its second day on the stock market.
Shares in the AI company had closed about 17% higher than its initial public offering price yesterday.
Its record-breaking IPO was seen as a vote of confidence in the AI trade – but it has failed to stem the tech sell off today, with European and Asian stock markets falling.
That sell-off is spreading to the US now too – the tech-heavy Nasdaq 100 is down 1.2% at the open, adding to a 2.2% decline yesterday. The S&P 500 is down 0.5%.
Updated
Anthropic shares are poised to fall sharply when the US market opens in the next few minutes.
Kathleen Brooks, of the broker XTB, says:
Overall, Anthropic’s New York Stock Exchange debut was solid, rising 17% on Thursday, however, the stock is now firmly in double figures and trading just above $91 per share.
This is still well above the IPO price of $83. This is now the level to watch. If the sell off gathers pace in the coming sessions, then it would be at risk of dipping below this level. The issue for investors is that a wide-spread risk aversion has gripped markets as investors fret about several issues at once. This includes the leadership of Nvidia, the excessive spending to fund the AI build out and AI labs, rising interest rates, and the change of power to the Democrats in the US Congress.
She adds that the Anthropic IPO does not fix concerns around the stability of the AI trade.
[It] does nothing to address these issues, so they carry on impacting market sentiment. Markets have also had to digest new risks including Apple’s announcement that it is developing its own AI agent to do tasks on behalf of users, which is a big challenge to Anthropic’s models, and concerns that AMD has also been breaching trade rules in China.
The neoclouds, which were initially buoyed by Nvidia’s results, have come under more pressure this week. CoreWeave has fallen another 20% this week, and is set to open down another 3%. Not even news that Jensen Huang’s charity was investing in CoreWeave helped to stabilise the stock price. This is a sector in distress, and investors are wondering if it is the canary in the coalmine.
Updated
Anthropic shares are now down 10% in pre-market trading, as an AI sell-off picks up in global markets.
In Europe, chip companies such as ASML and Infineon Technologies are down by 6% and 5% respectively. It follows a wave of selling in Asia, with the likes of TSMC, Samsung Electronics and SK Hynix closing down 4.7%, 7% and 5.9% respectively.
Advanced Micro Devices (AMD), which was the victim of a short seller attack yesterday, is down 6.7% in pre-market trading. Nvidia is down by about 3% in pre-market.
The price of gold is also continuing to fall today, heading for its biggest weekly decline since March.
The yellow metal is down 1.1% to $3,578.48 per ounce, touching its lowest level since September 4, 2025 at $3,513.54 earlier.
Much of the pressure on gold prices has come from strong economic data and high inflation in the US, which has fed expectations of interest rate hikes. Gold typically becomes less appealing to investors when rates are high as the metal does not pay them a yield.
Here’s the view from Dominic Schnider, head global FX & commodity, and Giovanni Staunovo of UBS Global Wealth Management:
The sharp price decline warrants revisiting the drivers of last year’s gold rally into 1Q26. Rising expectations of Fed rate cuts, tariff concerns, questions about Fed independence, and perceptions that the US administration favoured a structurally weaker currency created a supportive backdrop.
Higher inflation has since shifted rate expectations toward hikes. Concerns about Fed independence have eased as the Fed has raised rates without material intervention from the US administration. Meanwhile, an AI-driven investment boom has supported US economic activity.
Taken together, these developments could be interpreted as driving a full retracement of gold’s rally toward USD 3,500/oz. While this interpretation has some merit, we believe the market is overly optimistic about US economic resilience and may overestimate both the level and duration of higher interest rates.
We expect inflation to level off and US activity to moderate slightly in 2027, allowing rate expectations to shift from further hikes to a pause, followed by cuts later in the year. Beyond these cyclical factors, structural headwinds for the USD remain a topic, notably the US fiscal deficit trajectory.
UK and EU agree 'reset deal'
The UK and EU have agreed a reset deal on food and drink, emissions trading and a new youth mobility scheme, Downing Street has said, although talks on the level of tuition fees EU students will pay remains unresolved.
A No 10 spokesperson said both sides had agreed timelines for implementing a youth mobility scheme, a sanitary and phytosanitary agreement and a link between their emissions trading systems, with details due to be published in a joint statement later on Friday.
You can follow developments live on our Europe live blog with Jakob Krupa:
Related: UK says EU reset deal agreed but talks will continue ‘in some areas’ – live
AMD was also the victim of a short seller attack last night.
Shares in the $802bn US chip company fell by as much as 11% yesterday after reports connected to the short seller Hunterbrook raised concerns about its ties with China.
Hunterbrook Media raised concerns around AMD’s dealings in China, claiming that it leaves the company more vulnerable to US chip export restrictions and citing its extensive supply chain in the country.
It said:
Most AMD processors face few export restrictions today. The trouble is that AMD’s growth story rests on the chips that face tighter restrictions.
Meanwhile its newsletter, The Bear Cave, also highlighted that AMD’s use of datacentre lease guarantees and backstops for unsold cloud capacity.
It wrote:
On the surface, its financials look solid. But a proverbial AI capex bank run could test just how solid they are.”
AMD has said in a statement that the report’s claims “misrepresent AMD’s business practices and relationships”.
It added:
AMD complies with applicable US export control laws and regulations and maintains rigorous processes to ensure compliance across our global operations.
Investors however still seem spooked – AMD shares are down by 5.4% in pre-market trading.
The UK’s stock market has a reputation for its rather meagre selection of tech stocks, which typically protects it from AI-driven sell-offs. But some of the pain is being felt here today too – the FTSE 100 is now down by about 0.9%, to its lowest level since June.
Its worst performer is the Polar Capital Technology Trust, a listed investment company that mostly backs tech companies and a range of chip stocks such as Nvidia, AMD and TSMC. Its shares are down 5% this morning.
California investigates Nvidia over whether chip exports ended up in China
California has served an investigative subpoena on Nvidia after a scandal that prompted the departure of co-founder and longtime chief executive Jensen Huang.
Rob Bonta, the US state’s attorney general, issued the subpoena as part of an investigation into whether exports of the California-based company’s advanced semiconductor chips ended up in China, contravening US restrictions.
He said:
The conduct of Nvidia and its former chief executive raises bright red flags, including about the ways in which the company may have misled investors.
Nvidia is in a messy, transnational situation but the underlying principle of our corporate securities law is clear: Companies cannot mislead their investors.”
The subpoena, issued on Thursday, followed Huang’s resignation a week ago after it emerged he had multiple affairs, including one with Alice Huang, a suspected Chinese spy.
Related: California investigates Nvidia over whether chip exports ended up in China
And in another warning sign that markets are unsettled today – Europe’s Stoxx volatility index has jumped to 25.9, its highest point since April.
Anthropic shares fall 6% in pre-market trading
Anthropic shares are now down 6% in pre-market trading, in a sign that the stock is likely to fall sharply in its second day of trading.
The AI developer closed its first day of trading on the US stock market yesterday about 17% higher than its initial public offering price. At the close, Anthropic shares were trading at just over $97 with a nearly $1.3tn total market capitalisation, $1.75tn fully diluted.
However worries continue to grow about a possible AI bubble in the stock market, with investors questioning whether companies can justify the huge amounts of spending and borrowing to fund the AI build out and astronomical valuations in the sector.
Earlier this month the US midterm election result triggered a tech sell-off amid speculation that a Democrat-controlled Congress could lead to tighter control of AI and datacentre construction.
Meanwhile the resignation of Nvidia CEO Jensen Huang has thrown one of the most valuable companies in the sector into uncertainty as it seeks a new leader.
British retail sales surge as households stockpile emergency supplies
Retail sales in Great Britain surged last month as the public rushed to buy products including tinned food and long-life milk, after the government issued a warning to stock up in case of a disaster.
The ONS has announced this morning that the volume of goods sold jumped 0.7% month-on month in October, defying economists’ consensus expectations of flat sales, as “preppers” took heed of the government’s Be Ready campaign to hold supplies to last 72 hours to survive a potential weather, cyber or other serious emergency.
It is a welcome bounceback for the industry after a poor September, which the ONS has revised down from a 0.4% fall to a 0.6% fall, fuelled in part by poor online sales of autumn and winter clothing because of unseasonably warm weather.
Fitzner said:
Supermarkets have told us that sales of long-life food items such as tinned food and UHT milk were boosted by the government’s ‘Be Ready’ campaign.
Related: Household rush to stockpile emergency supplies sends British retail sales soaring
European stocks fall as AI sell-off spreads
The AI sell-off is spreading this morning, with the European stock market also opening lower.
The Stoxx Europe 600, which tracks the biggest companies on the content, is down 1% and is on track to end the week down 4.5% – its worst performance since March.
The UK’s blue chip FTSE 100 index is holding up relatively well, down by just 0.3% today – no doubt helped by its lack of big tech companies. The German Dax is down 1.3% and the French Cac 40 is down 0.9%. Chip companies ASML and Infineon Technologies are down by 2.8% and 4.8% respectively as the rout in AI-related stocks continues.
Richard Hunter, head of markets at the broker Interactive Investor, says:
The huge capital investment in the buildout thus far, the possibility of datacentre slowdowns given the recent Democratic sweep and the Nvidia CEO resignation which raises questions around China and US national security all played a part in weakening the AI trade.
There is no doubt that AI is here to stay, and the Nvidia results earlier in the week were initially well received and proof that underlying demand is still far from being satisfied, but the heady stock valuations have led to inevitable doubts on the scale and timing of any ultimate payback.
He notes that in the UK, tech-focused investors and stocks have suffered this morning.
Stocks seen as being more tech-related were in the direct line of fire, with falls of 5% for Polar Capital and 3% for Scottish Mortgage and Computacenter.
A broad markdown elsewhere was enough to overwhelm any attempted offset from some buying in the defensive sectors, although again the overall losses were mild in comparison to the wider global weakness which is threatening to become something of a Santa rout, as opposed to the rally which had been anticipated.
The FTSE 100 has seen its own gains for the year shaved to 4.8%, and the index is now away from the record closing high which it threatened to breach only last week by the same amount.”
Emma Reynolds, chief secretary to the Treasury, is upbeat about the public borrowing figures this morning. She said in a statement:
Fiscal discipline underpins the decisions this government makes everyday. Britain is showing stand-out resilience despite the global impact of the conflict in Iran. We’re building on that.
This year we’ve cut borrowing faster than any other G20 country. Now we’re going to cut waste and bureaucracy by reprioritising spending and making public services more efficient with AI.”
Rob Wood, chief UK economist at the consultancy Pantheon Macroeconomics, notes that while the government will be pleased with the data this morning, “the October budget did little to address the more serious challenges facing the public finances.”
We continue to have doubts about the government’s ability to follow through on its fiscal plans, suggesting upside risks to borrowing in the coming years.
For now, we have to compare October’s data to the [Office for Budget Reponsibility’s] forecasts consistent with the spring statement, as the monthly profiles produced as part of budget 2026 have yet to be released.
But on that basis, government borrowing in the first seven months of the 2026/27 fiscal year is now estimated to have overshot the OBR’s expectations by £3.3bn, down from the £6bn estimated in last month’s figures, which ran to September. [Public sector net borrowing] for October alone overshot the March 2026 forecast by £0.8bn.
We should get the latest profiles from the fiscal watchdog later today, but the OBR raised forecast public sector borrowing in 2026/27 by £17.7bn, of which £6bn had already fallen in the first six months of the fiscal year, meaning the residual would boost borrowing by £2bn if spread evenly over the final half of 2026/27. On that basis, borrowing for October in isolation undershot expectations by around £1.2bn.”
UK government borrowing rises less than forecast
And closer to home this morning: the UK government borrowed less than expected in October despite a rise in debt interest costs, in a boost for chancellor John Healey amid the pressure on Britain’s economy from the Middle East war.
The Office for National Statistics (ONS) said public sector net borrowing – the difference between government spending and income – was £17bn in October, about £800m higher than the same month a year ago. City economists had forecast borrowing would increase to £18bn.
In the financial year so far, public sector net borrowing was £111.3bn, the ONS said – £7.3bn less than in the same period last year.
Grant Fitzner, the ONS chief economist, said:
Borrowing so far this financial year remained lower than in the same period last year with receipts growing faster than spending. Income-related taxes’ receipts grew particularly strongly.
However, monthly borrowing was up on last October, partly down to higher debt interest.”
Related: UK government borrowing rises less than forecast in surprise boost for chancellor John Healey
SoftBank shares suffer worst day in over two years
More pain in the market today – shares in the tech investor SoftBank have suffered their worst day in more than two years amid worries around its aggressive bets on AI.
The Japanese firm is one of the biggest investors in Anthropic’s rival OpenAI, which slashed its fundraising target by $10bn last month in a funding round.
SoftBank shares are down by more than 14% today, putting it on track for its worst day since August 2024.
This week founder Masayoshi Son told a tech conference in Tokyo that he regretted not investing in Anthropic before its IPO.
The Financial Times reported he said:
We did have meetings [about investing in Anthropic]. But by that point, we had already decided to invest in OpenAI, and had already started doing so. So in that sense, there was a reluctance to pursue it further.
This is an example of one of my mistakes.
Yesterday Anthropic became one of the most valuable publicly traded businesses in the world, ending its first day on the US stock market about 17% higher.
Chief executive Dario Amodei said the IPO “puts the company in a stronger financial position, and in doing so only strengthens our resolve to do the right thing.”
Anthropic has seen explosive growth in revenue every year of its existence – sometimes more than 1,000% – according to its investor prospectus, filed at the end of October. The company brought in $16.2bn in the first six months of 2026, up from $4.6bn in revenue for all of 2025.
Related: Anthropic closes first day of public trading at $1.3tn valuation after largest-ever IPO
Introduction: Asian stocks headed for worst week since 2020
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
Anthropic’s historic IPO yesterday certainly lived up to the hype, ending the day at a whopping $1.7tn valuation – but it looks like has failed to allay investor concerns around an AI bubble.
Asian stock markets have sold off overnight, led by falls at big chip companies, and are now on track for their worst week since 2020.
In Taiwan, stocks dropped 6.7% to hit their lowest point since mid-April, deepening its weekly loss to more than 16%, and putting them on track for their worst five-day rout since 1990. TSMC, a leading chip manufacturer and by far the most valuable company in Taiwan’s stock market, fell by about 6%.
South Korean stocks also fell more than 5% to their lowest in more than nine months, with Samsung Electronics and SK Hynix both falling by about 7%. The falls have pushed the MSCI EM Asia equity index down more than 4% to levels last seen in early April – the index has lost nearly 9% this week, and is on track for its worst week since mid-March 2020.
Meanwhile Anthropic itself has fallen by 4.7% in after hours trading to $92.60, below its lowest level yesterday.
Its IPO has failed to ease worries around the AI trade, as investors increasingly question whether companies can deliver the returns necessary to justify the billions of dollars being poured into the AI buildout.
Jim Reid, of Deutsche Bank, notes that Hong Kong’s Hang Seng index is now also approaching bear-market territory as it is down almost 20% from its peak in January.
The CSI 300 (-1.85%), Shanghai Composite (-2.10%), and Australia’s S&P/ASX 200 (-1.58%) are also posting notable declines. The downward momentum is continuing in futures with contracts on the S&P 500 (-0.50%), Nasdaq 100 (-0.98%) and Stoxx (-1.70%) all notably lower with Europe catching down.
The risk-off tone has also weighed on a wide variety of other asset classes, with gold (-2.68%) sliding to a 14-month low of $3,625/oz yesterday and down another -2.2% this morning. Bitcoin (-1.25%) has fallen to its lowest level since early July, and US HY credit spreads (+6bps) reaching their widest level since May at 344bps.
Matters haven’t been helped by the latest geopolitical headlines, which helped push energy prices higher and added to fears about inflationary pressures.
Among others, Axios reported that the White House had asked the Pentagon and intelligence experts for their view on how Iran would respond to the different strike scenarios prepared by the US military. So that echoed the previous evening’s report in the New York Times that President Trump was considering plans for further strikes on Iran.
The agenda
7am GMT: ONS public finances, ONS retail sales
3pm GMT: University of Michigan’s consumer confidence report for November
Today: UK-EU summit – Andy Burnham will meet António Costa, President of the European Council, and Ursula von der Leyen, President of the European Commission, in Brussels on 20 November 2026 for the second UK-EU summit